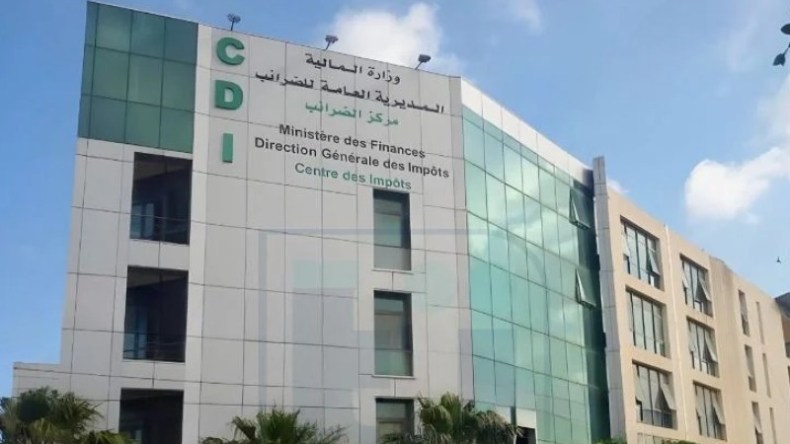
Algeria's tax services have ceased accepting paper declarations for specific taxpayer categories, mandating electronic submissions as part of a broader drive to modernize financial processes. Electronic declaration is now compulsory for those operating under the real profit system and the simplified system for non-commercial professions, marking a significant shift from traditional methods. This initiative also introduces, for the first time, remote payment options for taxes and fees for taxpayers affiliated with tax centers, neighborhood centers, and inspectorates, enhancing convenience and efficiency. However, the tax administration has granted an exception, permitting the submission of declarations related to the year 2025 in paper form for a temporary period.
New Electronic Declaration Mandates
The new instruction implements provisions outlined in Article 111 of Law No. 25-17, dated December 14, 2025, which encompasses the Finance Law for 2026. This legal framework underpins the transition to digital tax processes. Prior to December 31, 2025, electronic tax obligations were exclusively mandated for taxpayers affiliated with the Directorate of Large Enterprises, limiting the scope of digital submissions. This marks a significant expansion of the electronic filing system within Algeria's tax framework, extending its reach to a broader segment of taxpayers. The move signifies a concerted effort by the Algerian tax authorities to streamline operations and improve compliance through digitalization.
Under the updated regulations, taxpayers operating under the real profit system and the simplified non-commercial professions system are now required to submit several key documents electronically. These include Declaration Series 6 No. 50, Annual Results Declarations 'TA' No. 11-6 and its appendices No. 2-6, Non-Commercial Profits Declaration No. 13-6, Client Statement No. 3-6, and the Annual Salary and Wages Declaration No. 29-6. The mandatory nature of electronic declaration specifically remains in effect for submitting Declaration Series 6 No. 50, reinforcing its central role in the new digital submission process and ensuring essential financial data is captured digitally.
Expanded Remote Payment Capabilities
The 'Jibayatek' system is undergoing a generalization process, extending its reach to encompass all operational tax services within Algeria. This expansion includes tax centers, neighborhood tax centers, inspectorates, and tax collectorates, aiming to standardize digital financial interactions across various administrative levels. The initiative broadens the scope of remote payment options for taxpayers. The payment of taxes and fees through electronic or remote means is now available to taxpayers affiliated with tax centers, neighborhood tax centers, and inspectorates. This option is accessible regardless of the specific tax system under which a taxpayer operates, providing widespread access to digital payment solutions. However, the tax administration has indicated that utilizing these electronic and remote payment methods remains optional for now, allowing taxpayers flexibility in their payment choices while encouraging adoption of the new systems.
Context and Exceptions
The Directorate General of Taxes issued Instruction No. 31/2026 on May 6, 2026, outlining the new electronic filing mandates. This instruction details the requirements for various taxpayer categories and sets the official timeline for implementation. Separately, an exceptional authorization has been granted for taxpayers to submit declarations for the year 2025 in paper form. This specific allowance was communicated via Instruction No. 46/2026, dated April 19, 2026, providing a temporary deviation from the electronic submission mandate for that particular tax year to ease the transition. This exceptional measure ensures that taxpayers have ample time to adapt to the new digital requirements without immediate penalties for the prior year's declarations.
For taxpayers operating under the lump-sum tax system, the option to submit their declarations electronically is available. However, this method is not yet compulsory for this group. The tax administration has indicated that electronic submission for lump-sum taxpayers remains optional at this time, allowing them flexibility in choosing their preferred declaration method while encouraging adoption of digital processes. This phased approach aims to ensure a smooth transition across all taxpayer categories within Algeria's modernized tax framework.